

Fifth Third: 53 Mobile Banking
by Fifth Third Bank
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
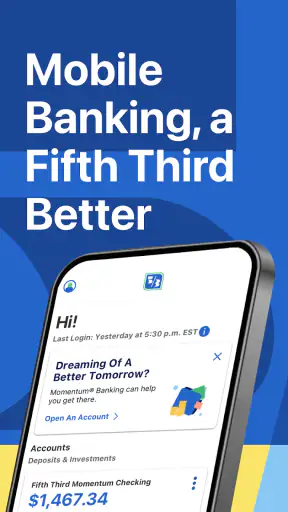
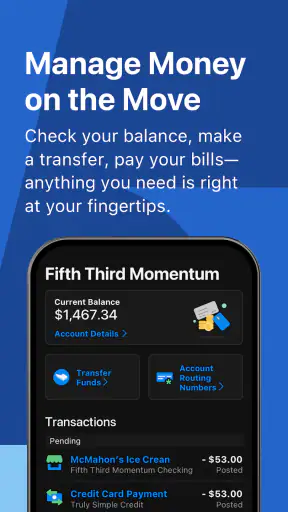
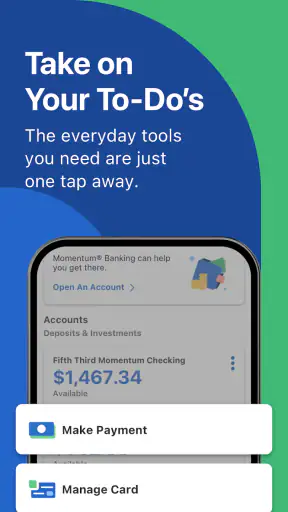
 Analysis by Getfullapps
Managing a household bank account is rarely about checking a balance once and walking away. In real life, one person may need to confirm whether a payment cleared, another may want to check available money before shopping, and everyone benefits when routine banking does not require a trip to a branch. I found Fifth Third: 53 Mobile Banking most useful in that everyday space: it puts Fifth Third Bank access on a phone while keeping each customer’s banking relationship separate.
The app is free, belongs to the Finance category, and is developed by Fifth Third Bank. Its store summary, “If your phone is on, your bank is open,” captures the basic appeal without telling the whole story. The real value is convenience for existing Fifth Third customers, especially when a household needs quick access at different times of day. It is not a general-purpose money manager for every bank, and that distinction matters before downloading it.
How it works in a shared household
Imagine a couple preparing for a busy weekend. One person is about to pay for groceries and wants to check the account first. The other is away from home and needs to confirm whether a recent transaction has appeared. With a mobile banking app, both people can deal with those small questions from their own phones instead of passing around a device or waiting until a computer is available.
That convenience does not mean the app turns one phone into a shared household dashboard. Banking access is personal, so each user should treat their own sign-in as their own responsibility. I would not recommend saving one person’s credentials for another person to use, even when both people share finances. A shared device can be practical, but it also increases the chance that the wrong person sees account information or performs an action under someone else’s session.
This is where the app works best: each adult uses the application independently, checks the information relevant to them, and discusses household decisions outside the app. It can support coordination, but it should not be mistaken for a family-control tool. I did not find a reason to treat it as a substitute for agreed household rules about spending, privacy, or who is authorized to make changes.
For a person who already banks with Fifth Third, the phone experience is much more convenient than relying only on branch visits or desktop banking. For someone who wants to connect accounts from several unrelated banks in one place, a broader financial aggregator may be a better fit. Those services can provide a wider view, while this app is focused on the Fifth Third relationship.
Starting with the right account boundaries
Setup should begin with a simple question: whose banking relationship is being accessed? The answer affects how the app should be used in a household. A joint-account customer may need to coordinate spending with another account holder, while a person with an individual account should not assume that a partner, roommate, or older child should use the same login.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I like this boundary because it keeps responsibility clear. If an account holder checks activity, that person knows the information belongs to their authenticated banking session. If several people use one device, I would make a habit of signing out or otherwise ending the session when finished, particularly in a home where guests, children, or service workers might pick up the phone.
The app runs on Android devices using at least OS version 9, which makes it accessible to many phones still in ordinary use. Its current version is 5.26.0, so keeping the application updated is sensible when banking is involved. I would also avoid installing it on a device that no longer receives security updates, because the safety of mobile banking depends on more than the app itself.
One practical setup tip is to decide where notifications and account information may appear before using the app regularly. A lock-screen preview can be convenient, but it may also reveal financial details to anyone who sees the phone. The better choice depends on the household’s privacy situation. A parent with a private phone has different concerns from roommates sharing a tablet or a family passing one device between users.
Coordinating without mixing up responsibility
Mobile banking is particularly helpful for short coordination tasks. Before transferring money between household accounts, paying a bill, or making a larger purchase, I can use the app to check the current picture rather than relying on memory. That reduces the awkward “did you already pay that?” conversation, although it does not remove the need to communicate.
My preferred workflow is deliberately simple. First, the account holder checks the account in the app. Next, the household agrees who will handle the payment or purchase. Finally, the person responsible confirms the result later. This avoids two people acting on the same assumption, which can happen when everyone has access to partial information but nobody has clearly accepted responsibility.
There is also a useful distinction between seeing an account and managing a household budget. The application can be convenient for checking banking activity, but a family may still need a separate shared note, spreadsheet, or budgeting service for categories such as rent, groceries, school costs, and subscriptions. I would not expect a bank app alone to explain the full financial arrangement of a household.
That limitation is not a flaw unique to this product; it is a trade-off. A focused bank app can feel clearer and less cluttered than a financial dashboard that imports information from everywhere. In exchange, it may not provide the broad planning view a household wants. I would choose the focused approach for daily account access and add another tool only if the family truly needs cross-bank planning.
Age, trust, and who should use it
The app has an Everyone content rating, but that label should not be confused with permission to give a child unrestricted banking access. Financial maturity, account ownership, and trust are separate questions. A young person may be able to use a phone comfortably while still needing an adult to explain balances, pending activity, and the consequences of a payment.
For teenagers or older children, I would keep the account boundary especially clear. If the child has an appropriate account and is authorized to use mobile banking, the adult should explain what the login protects and why credentials should never be shared casually. If the child is only helping with a household task, showing them information on the adult’s phone may be safer than handing over permanent access, depending on the family’s arrangement.
The same caution applies to elderly relatives or anyone who is less comfortable with mobile security. The app may reduce the need to travel, but a helper should not quietly take over the account. Walking through the process together preserves the account holder’s control. I would be wary of any household routine where one person keeps another person’s password or regularly performs banking without the owner understanding what is happening.
Trust also matters between adults. A joint household does not automatically mean every account should be visible to every person. Some couples combine finances completely, while others share bills but retain individual accounts. This application can fit either arrangement only when the people involved agree on access. It cannot resolve a disagreement about privacy, and no banking interface should be expected to do so.
What daily use feels like
In ordinary use, the strongest part of a mobile banking app is speed. I can reach for the phone when a question appears instead of postponing it until I am at a computer. That is valuable when a household is making a time-sensitive purchase, checking whether money is available, or trying to reconcile a transaction while a receipt is still in hand.
The experience is also more natural for people who do most of their digital life on a phone. Someone who rarely opens a laptop may find mobile access less intimidating than a full desktop banking site. The app’s long presence in the market, released on November 16, 2011, also shows that this is an established mobile banking product rather than a brand-new experiment.
Still, I would not use the phone as the only place to think about important financial decisions. A small screen encourages quick checks, and quick checks can become rushed decisions. For reviewing a complicated month, comparing several accounts, or planning a major change, a larger screen or a dedicated budgeting method may be easier to understand.
Another trade-off is that convenience raises the importance of phone security. A strong device passcode, current operating-system updates, and careful handling of alerts are basic parts of using any banking app responsibly. The application can make access easier, but it cannot protect a household from every mistake involving an unlocked phone, a shared password, or a deceptive message.
Where it fits among banking alternatives
Compared with visiting a branch, the app is better for routine checks that do not require face-to-face help. It is available when the phone is available, which can save time for people with work, childcare, or mobility constraints. A branch may still be preferable for a complicated issue, a sensitive conversation, or someone who wants personal assistance.
Compared with Fifth Third’s desktop banking experience, mobile access is more immediate but less spacious. I prefer a phone for quick verification and a computer for careful review. That is not a criticism of the app so much as a reminder that the best interface depends on the task.
Compared with a third-party budgeting app, this product has the advantage of being tied to the bank account rather than trying to assemble a household picture from multiple services. The trade-off is narrower scope. If your finances are spread across several institutions and you want one combined spending plan, a specialized budgeting application may serve you better. If most of your banking is with Fifth Third and you mainly want direct access, adding another layer may only create extra work.
I also would not choose it solely because it is free. Free is welcome, but the important question is whether it matches your bank and your household habits. Someone who does not have a Fifth Third relationship has little reason to install it, while an existing customer may find the convenience worthwhile even if they continue using other tools for long-term planning.
Scale, support expectations, and trust
The app has a 4.7 average from around 217 thousand ratings, with more than a million installs. Those figures suggest that many people are comfortable using it, but they should not replace personal judgment. A high rating does not guarantee that every phone, account arrangement, or household workflow will feel equally smooth.
Its age rating of Everyone makes it broadly approachable, and the free price removes a financial barrier to trying it. Even so, the audience is not “everyone” in the practical sense. The useful audience is Fifth Third customers who want mobile account access and can manage the security responsibilities that come with it.
I would also remember that a large user base can create a false sense of familiarity. Banking apps deserve more care than ordinary shopping or entertainment apps because the consequences of a mistake are more serious. Before making a payment or other important change, I would slow down, verify the account context, and avoid acting from a notification or message that seems unusual.
The developer name is visible as Fifth Third Bank, which is reassuring for customers looking for the bank’s own application rather than an unrelated finance tool. I would still install only from the official app marketplace and check the developer carefully, especially when searching on a shared family device where someone else may select the first result.
My household verdict
I recommend Fifth Third: 53 Mobile Banking to existing Fifth Third customers who want quick, direct access from Android and who are comfortable keeping banking credentials personal. It is especially useful for households that need frequent balance checks and simple coordination without turning every small question into a branch visit or desktop session.
I would skip it if your main goal is a combined view of accounts at many banks, a full household budgeting system, or a child-focused financial-control experience. It is also not the right answer for a family that has not agreed on who may access which accounts. No convenient interface can substitute for clear boundaries.
For shared households, my advice is to let each authorized adult use their own access, keep the phone protected, limit lock-screen exposure, and agree outside the app who is responsible for each payment. Those habits make the application more useful without pretending it can manage the family relationship itself.
Overall, this is a focused banking tool rather than an all-in-one financial planner. I value it for the small, frequent moments when I need reliable access to a Fifth Third account, and I think that is where it earns its place. Its best feature is not complexity; it is giving the right account holder a practical way to check and coordinate banking without unnecessary delay.
Pros
- Quick access to balances, transactions, deposits, and transfers
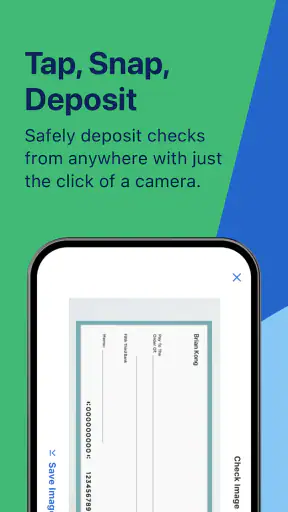
- Mobile check deposit saves a trip to a branch
- Bill pay and scheduled payments are convenient
- Card controls help manage spending and security
- Biometric login makes sign-in fast on supported devices
Cons
- Some features may require enrollment or account eligibility
- Mobile deposit limits can vary by customer and account history
- App performance may depend on device and network quality
- Certain banking services still require contacting support
- Users outside Fifth Third’s service area may have limited access
FAQs for Fifth Third: 53 Mobile Banking
What can I do with the Fifth Third: 53 Mobile Banking app?
Fifth Third: 53 Mobile Banking is designed to handle many everyday banking tasks from an Android or iOS device. After signing in, you can typically review account balances and transaction history, transfer money between eligible accounts, deposit checks using your phone’s camera, pay bills, manage eligible cards, locate branches or ATMs, and receive account alerts. Available tools may vary depending on your account type and enrollment.
Is the Fifth Third mobile banking app safe to use?
The app uses standard banking security features, such as secure sign-in, encryption, device and session protections, and optional biometric authentication when supported by your device. However, no banking app can eliminate every risk. Download it only from the official Google Play Store or Apple App Store, keep your phone updated, avoid public Wi-Fi for sensitive activity, and never share passwords, one-time codes, or verification details with anyone.
Can I deposit checks through Fifth Third: 53 Mobile Banking?
Eligible customers can generally use the app’s mobile check deposit feature by photographing the front and endorsed back of a check, entering the amount, and submitting it for review. The images must be clear and meet the app’s instructions. Deposit limits, availability times, holds, endorsement requirements, and eligibility can differ, so check the current terms shown in the app before relying on deposited funds.
Does the app support bill payments and money transfers?
The app typically provides options for paying enrolled bills and transferring funds between eligible Fifth Third accounts or linked external accounts. Some transfers may require additional verification, have processing delays, or be subject to daily and monthly limits. Before confirming a transaction, carefully review the recipient, amount, date, and funding account. Features and transfer availability may depend on your account and enrollment status.
What should I do if I cannot log in or notice suspicious activity?
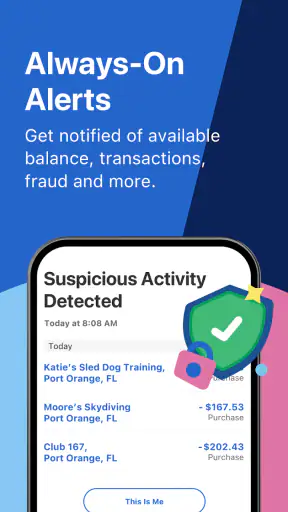
If you cannot access the app, first check your internet connection, update the application, and use the official password or username recovery options rather than repeatedly guessing credentials. If your phone is lost, your login details may be exposed, or you see an unfamiliar transaction, contact Fifth Third through an official channel immediately. Do not use phone numbers or links received in unexpected messages.

Fifth Third: 53 Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via itconsumermobileappssupport.bancorp@53.com, visit https://www.53.com/, or review their https://www.53.com/content/fifth-third/en/privacy-security/online-privacy-policy.html.










